H2 2026
The State of US Private Equity Report

Executive Summary
In this report, we go deep into the PE landscape in the US. We share insights on entries, exits, multiples, add-ons, holding periods, growth rates, margins and much more. All the data in the report comes from Gain — The Private Markets Super App. Here is a summary of our key findings:
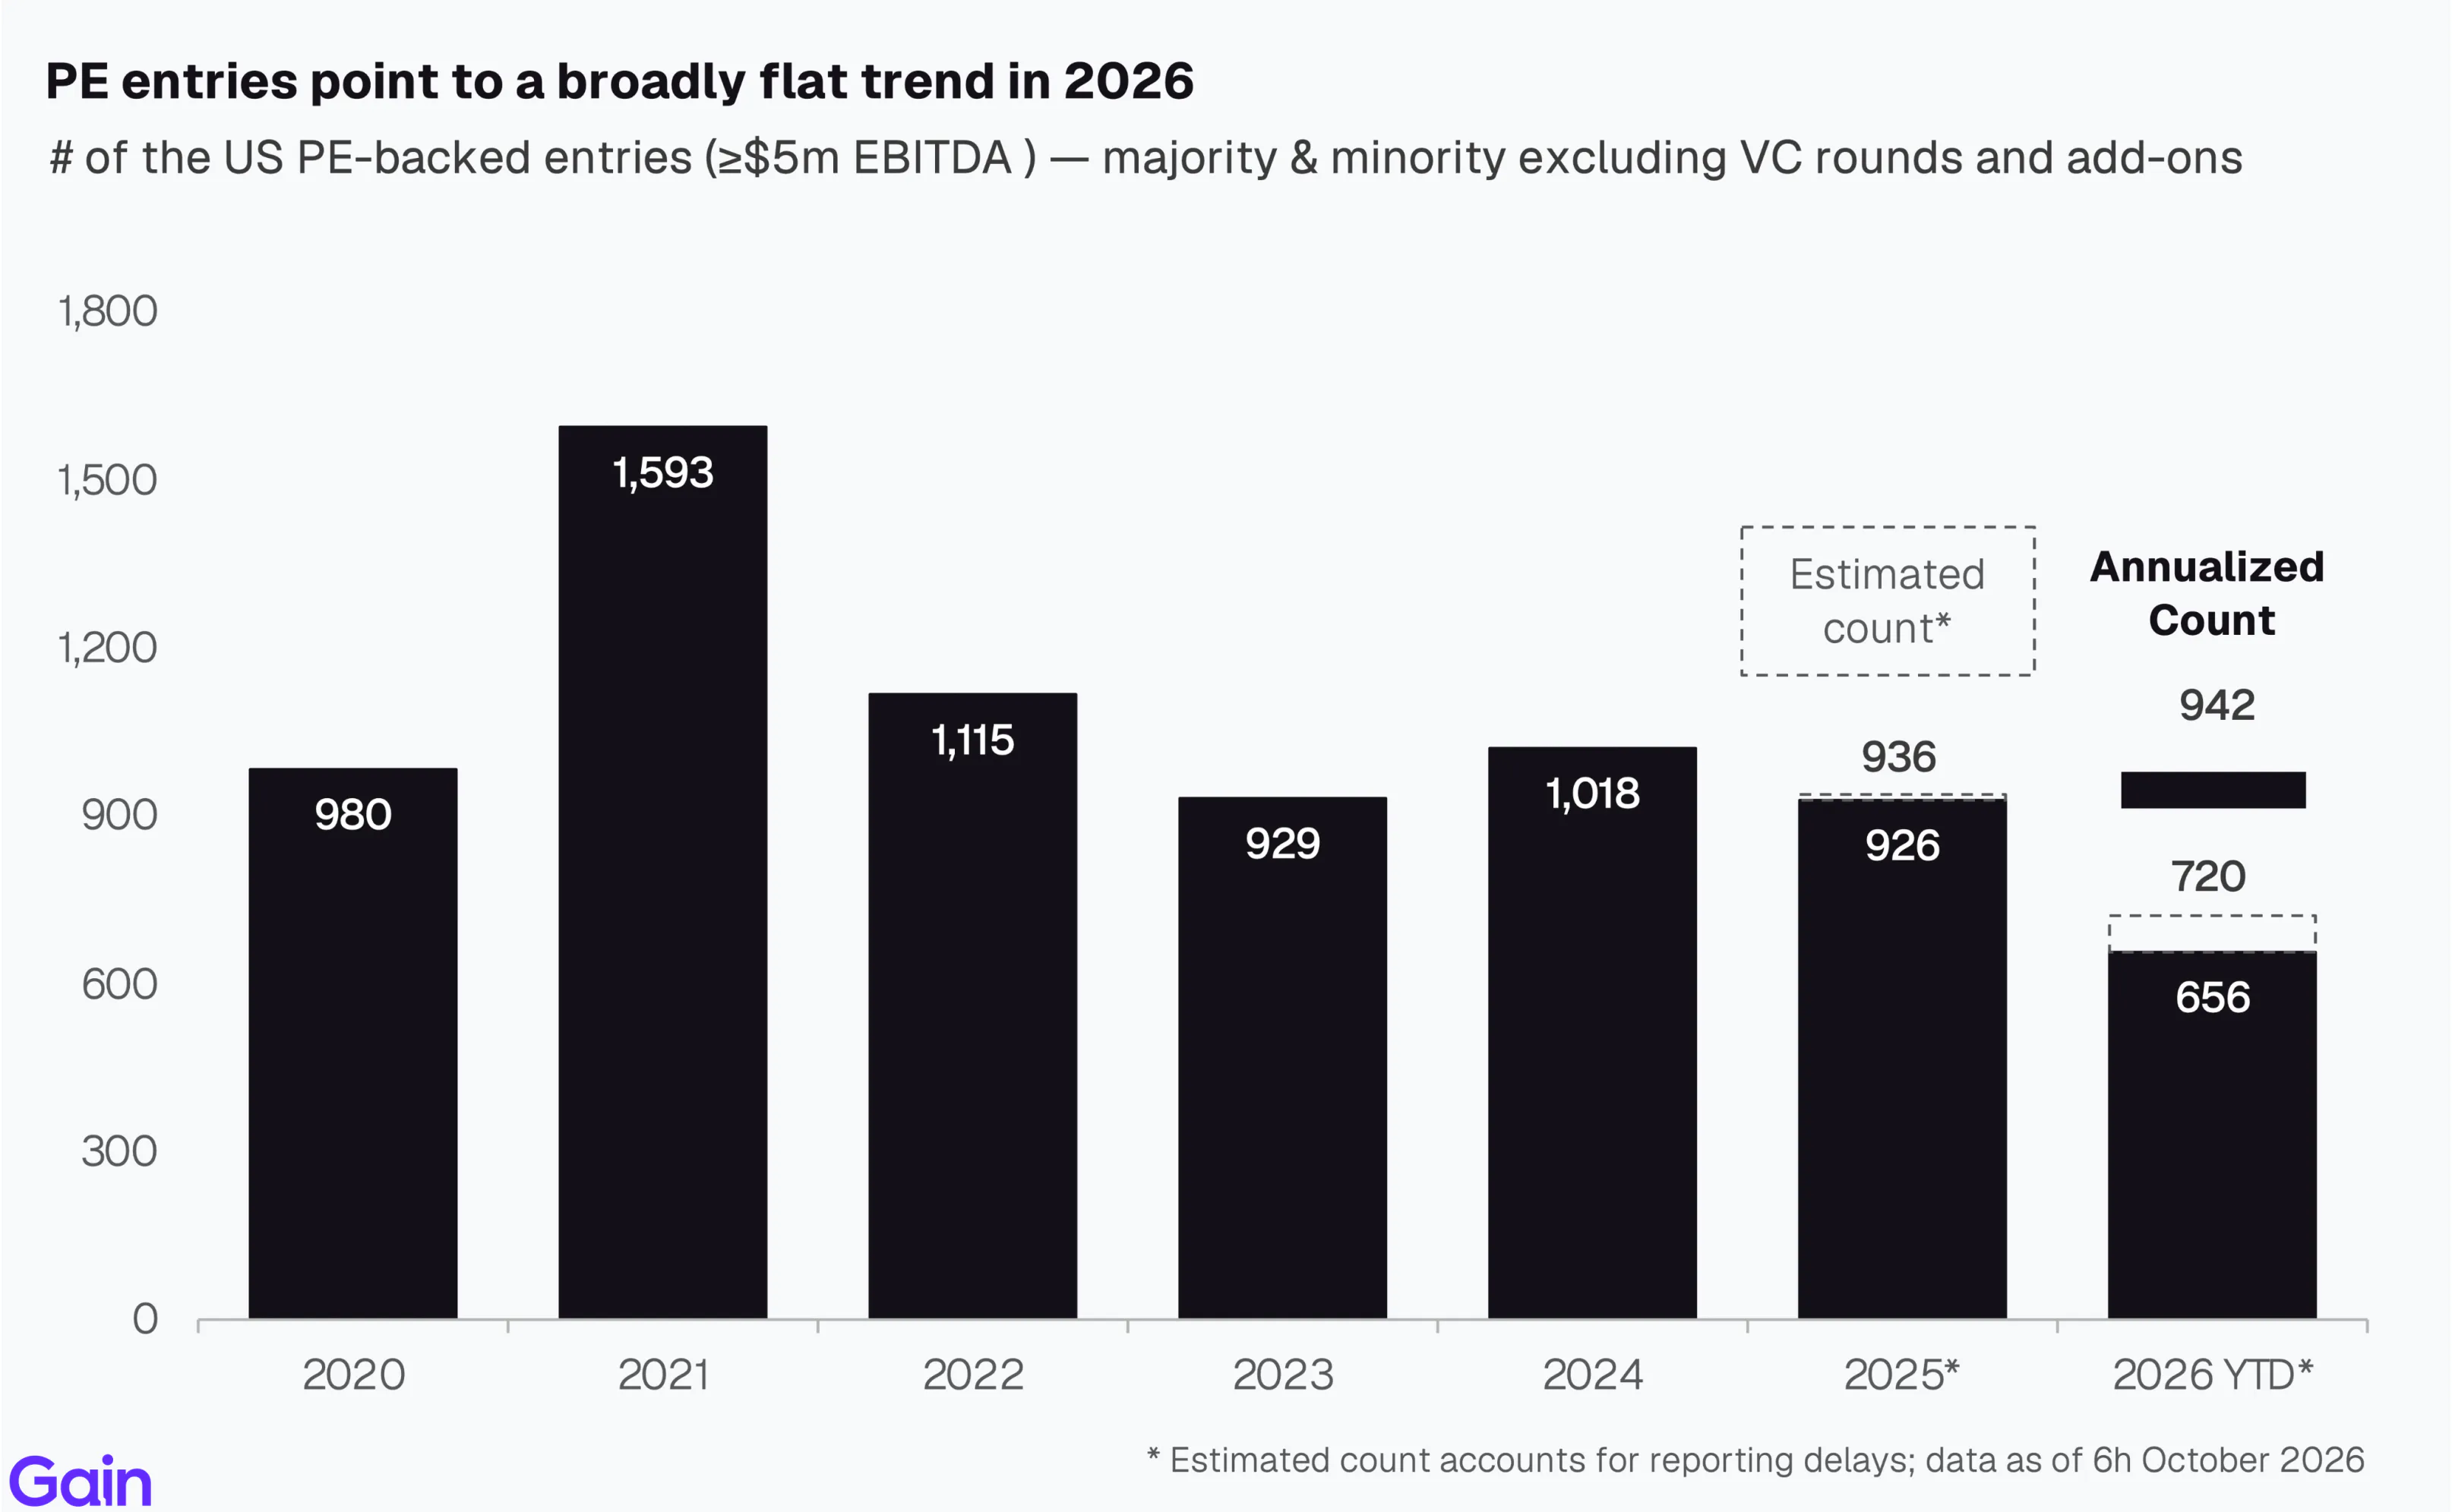
US PE entry count points to a flat trend in 2026. Geopolitical uncertainty and AI-led software disruption continue to weigh on dealmaking. Services sector remains relatively resilient.
PE entry deal value is lower in 2026 after a strong 2025. Large transactions (>$1bn EV) are returning back to normal levels.
Large software PE deal activity fell to its lowest share since 2018. AI-related uncertainty remains a key overhang. Energy delivered some of the largest US PE entries this year, displacing TMT which has held the leaderboard since 2020.
Buy-and-build continues to be the key value creation driver. Financials has 25 of the top 50 most-active consolidators with Services being the largest sector more broadly.
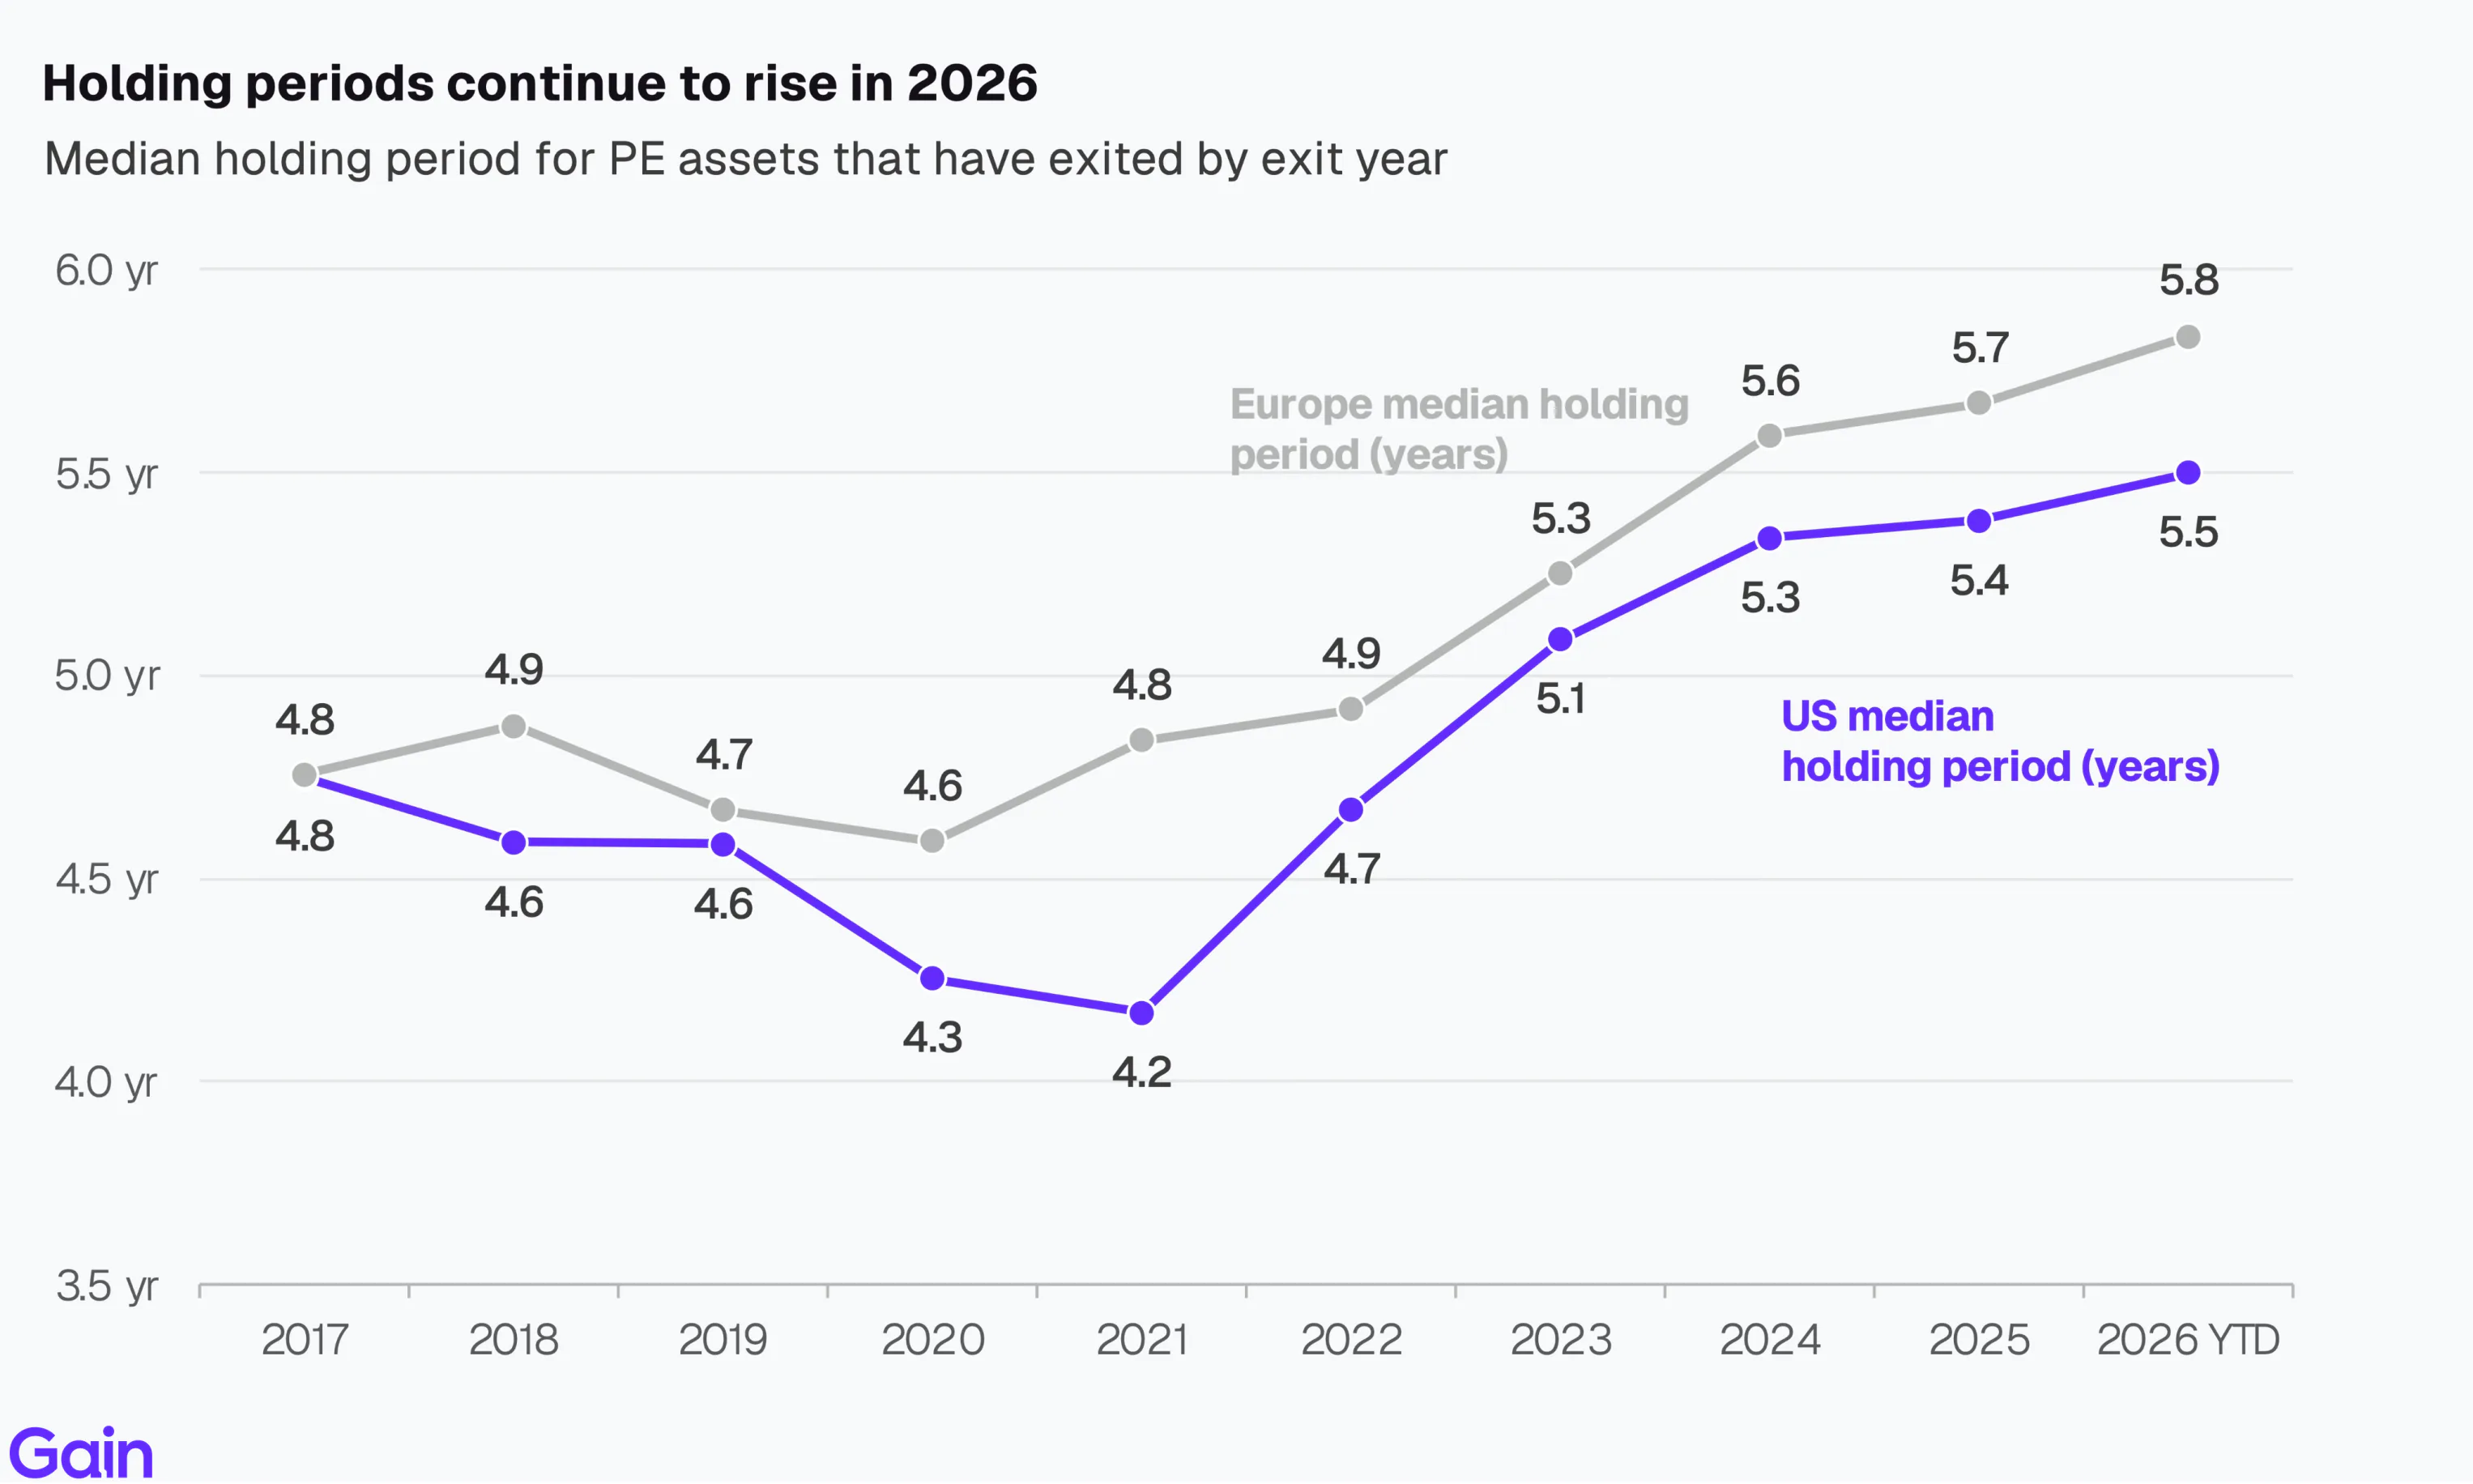
Holding periods continued to rise and are now up to 5.5 years. Exits from the 2021 vintage are running behind, with only 15% realized by year 4 vs a typical 25-30% range.
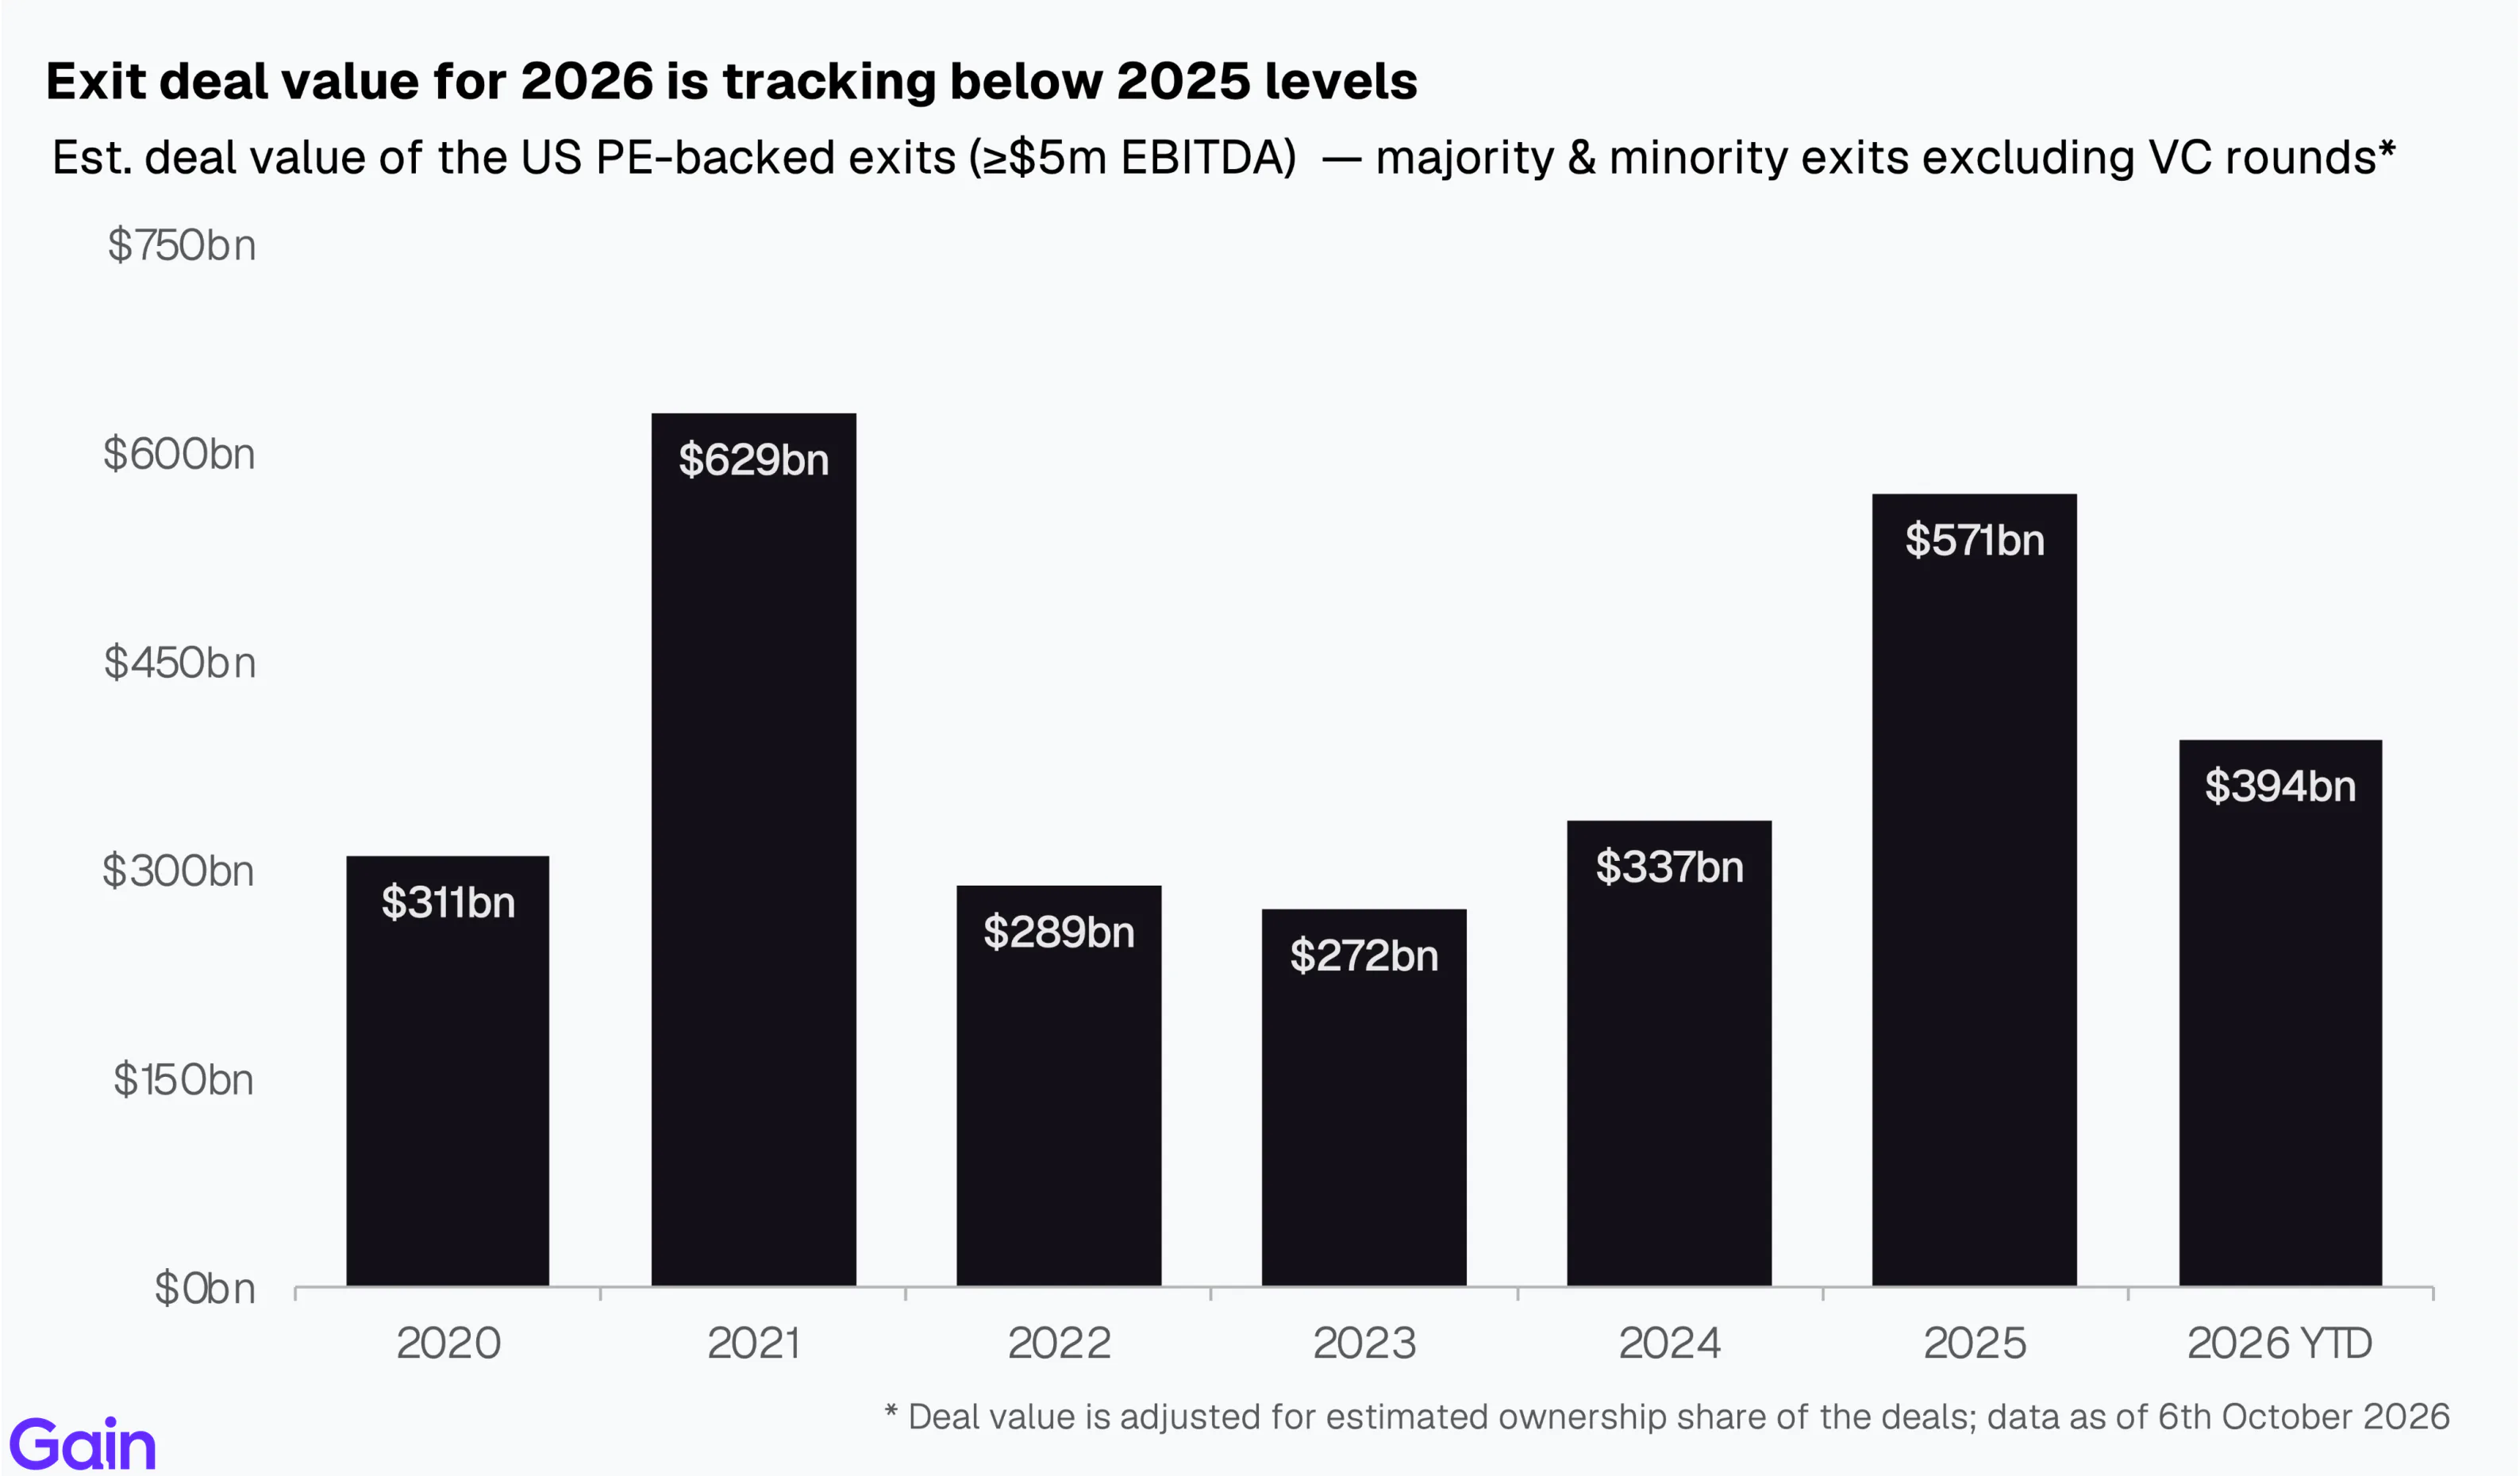
Exit deal value is lower in 2026. Exits in the Consumer sector remain particularly challenging on the back of slower growth and margin pressure.
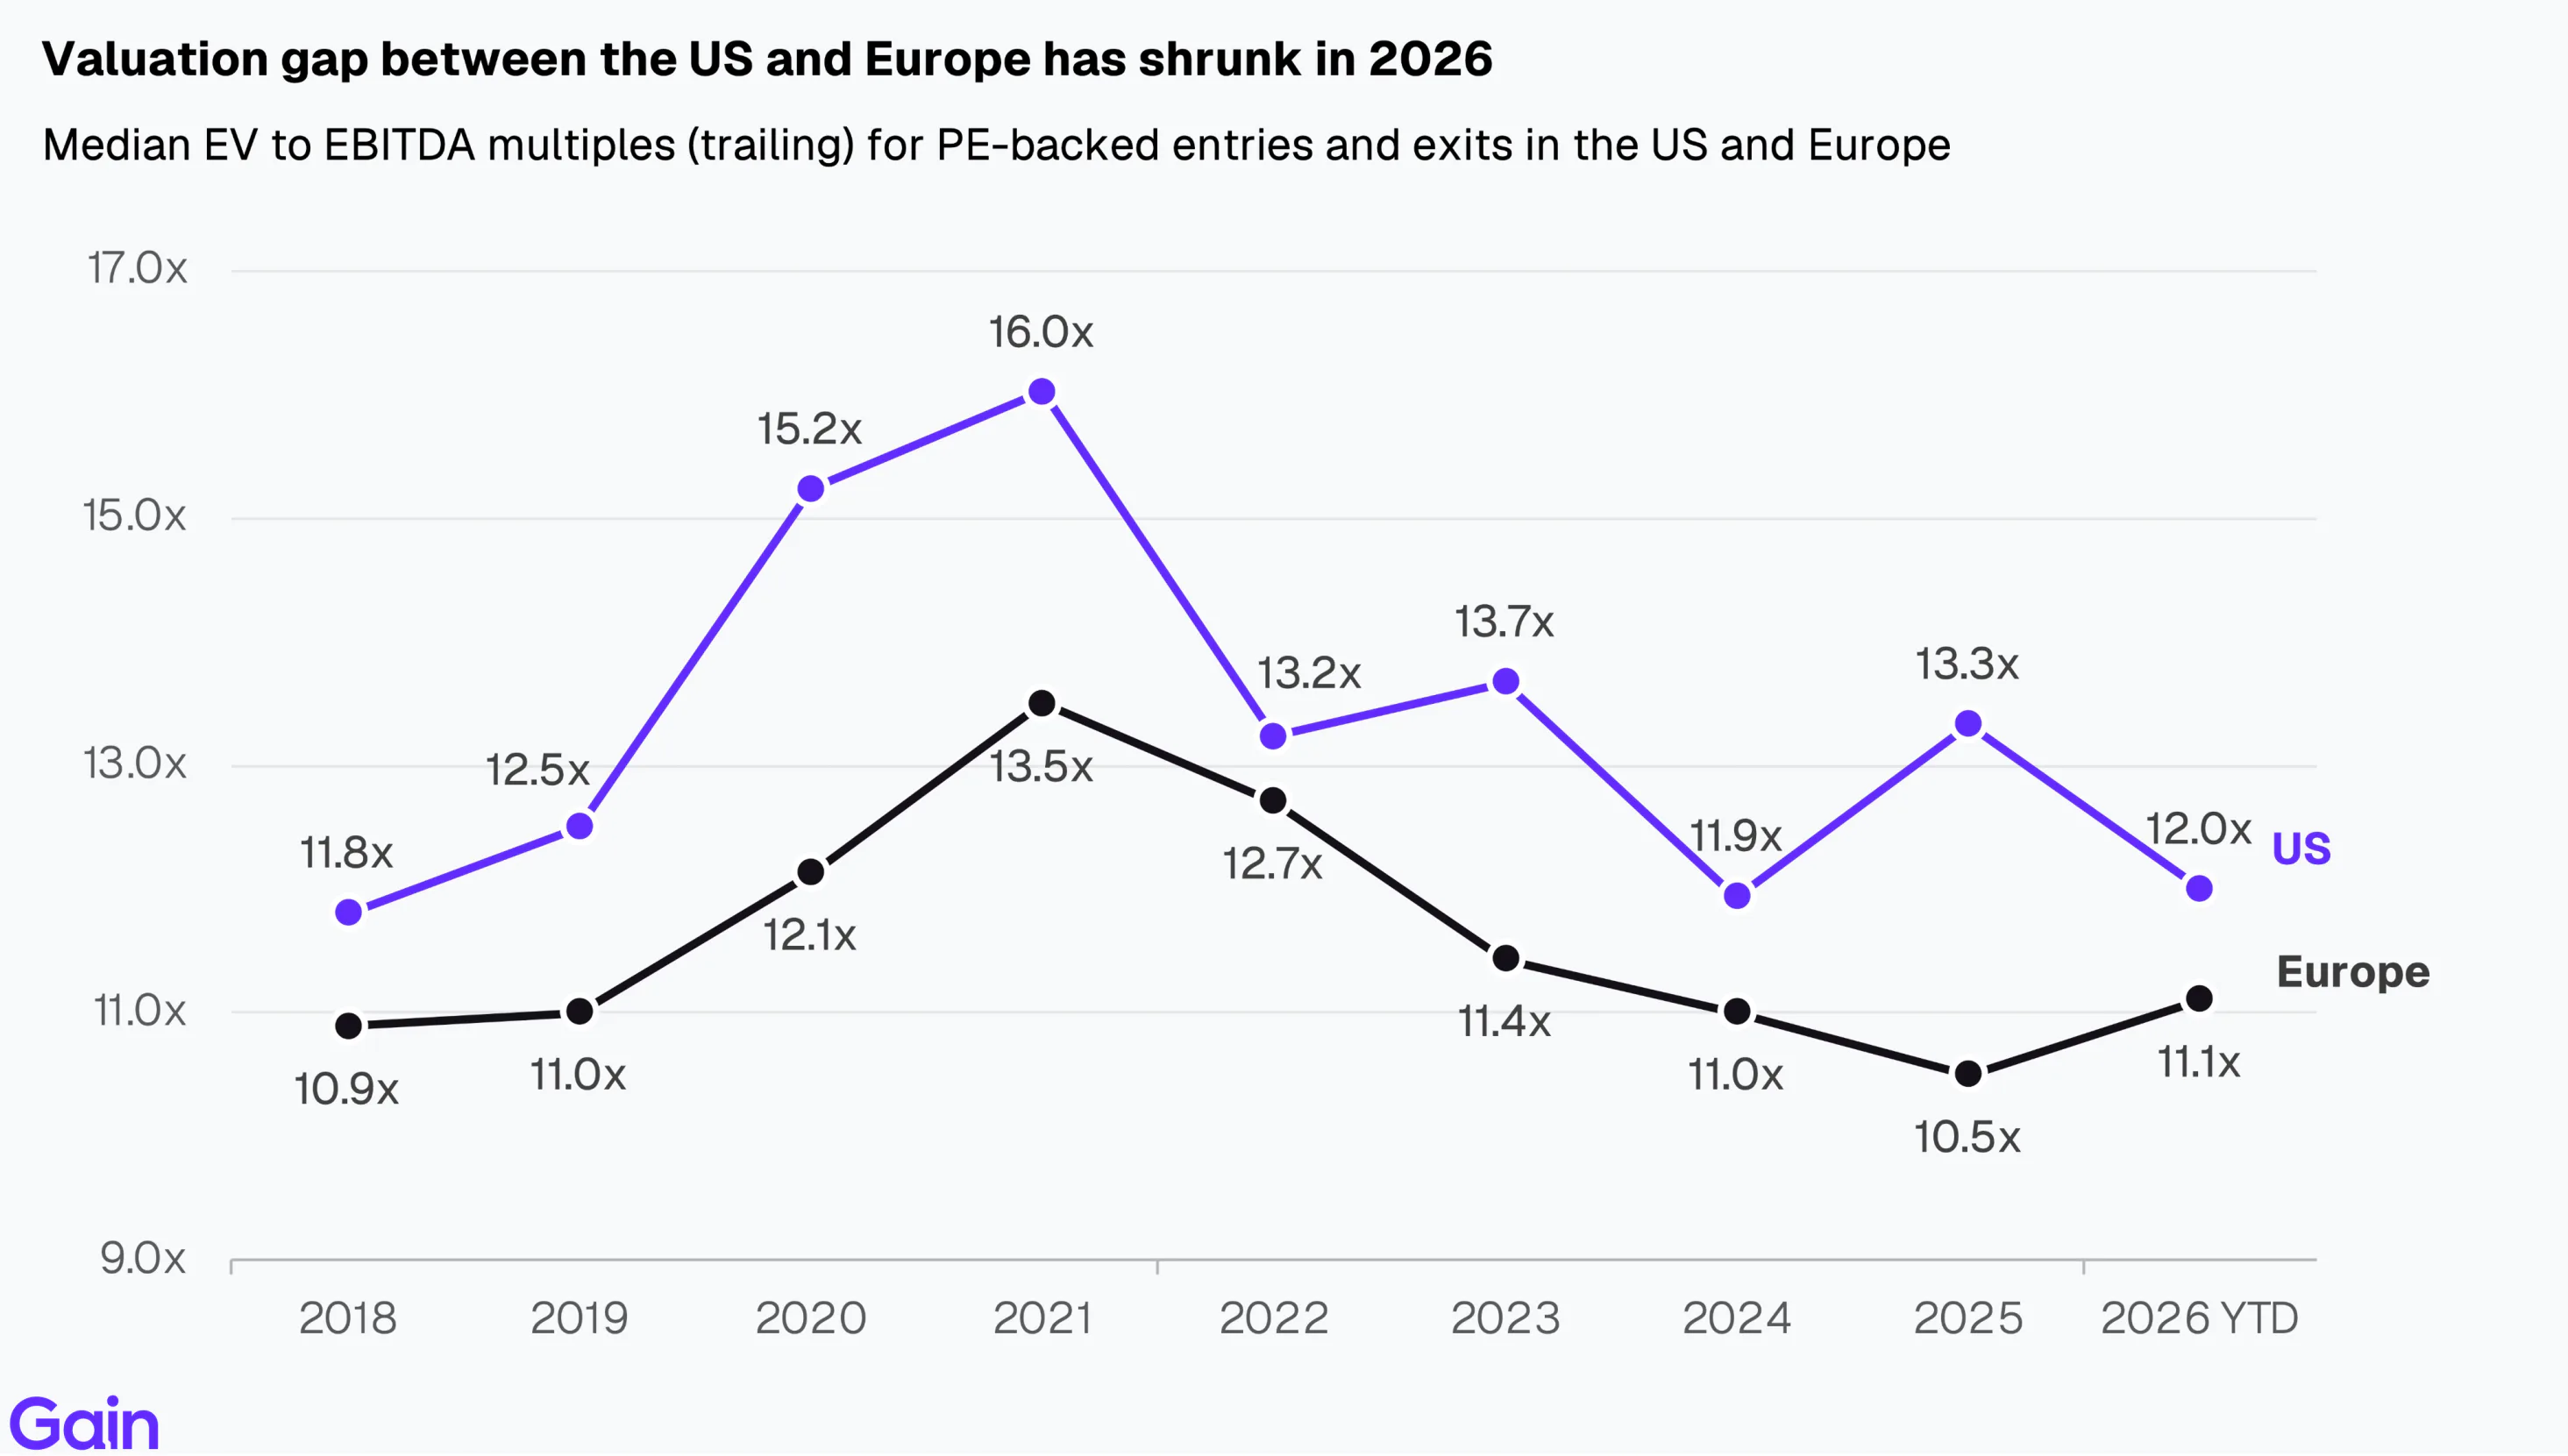
US PE multiples declined in 2026 to a median of 12x, but they remain above European levels. TMT saw the sharpest valuation drop.
If you have any questions about the data or the report, do not hesitate to reach out to insights@gain.ai.

Chapter 01: Entries
Annualized US PE entry count points to a broadly flat trend for 2026 (+1% YoY). Geopolitical uncertainty and AI-led disruption continue to weigh on dealmaking, with Services remaining relatively resilient while TMT faces greater headwinds.
US PE entry deal value is lower in 2026 following elevated levels in 2025. Strong deal value in 2025 was driven by a higher concentration of large transactions (>$1bn), which normalized in 2026.

PE entry activity from the largest PE investors shows a slight pullback. Investors continue to remain cautious amid geopolitical uncertainty and elevated financing costs.

Chapter 02: Exits
Exit deal value is lower in 2026. Exits in the Consumer sector remain particularly challenging on the back of slower growth and margin pressure. The gap in valuation expectations between buyers and sellers is also delaying larger exits.
Holding periods continued to increase to 5.5 years in 2026, extending a multi-year upward trend. However, the US assets have relatively shorter holding period than their European peers which can be partly driven by a lower concentration in Industrials and Consumer sectors which have had slower exits. Exits from the 2021 vintage are running behind, with only 15% realized by year 4 vs. a typical 25-30% range.
Exits in Consumer are most challenged, compared to the assets in the backlog (those held over 5 years). Consumer sector faces headwinds such as slower growth and margin pressure, which have clouded the outlook for these assets. In comparison, exits are healthier in Financial Services and Services.

Chapter 03: Add-ons
Add-on activity is expected to be broadly flat in 2026. Sponsors have remained focused on portfolio value creation, with buy-and-build being the key strategy.

Services is the largest sector for add-ons in the US, accounting for 38% of deals, followed by TMT (20%) and Science & Health (12%). Across all sectors, buy-and-build strategies continue to drive value through accelerated revenue growth and cost synergies.
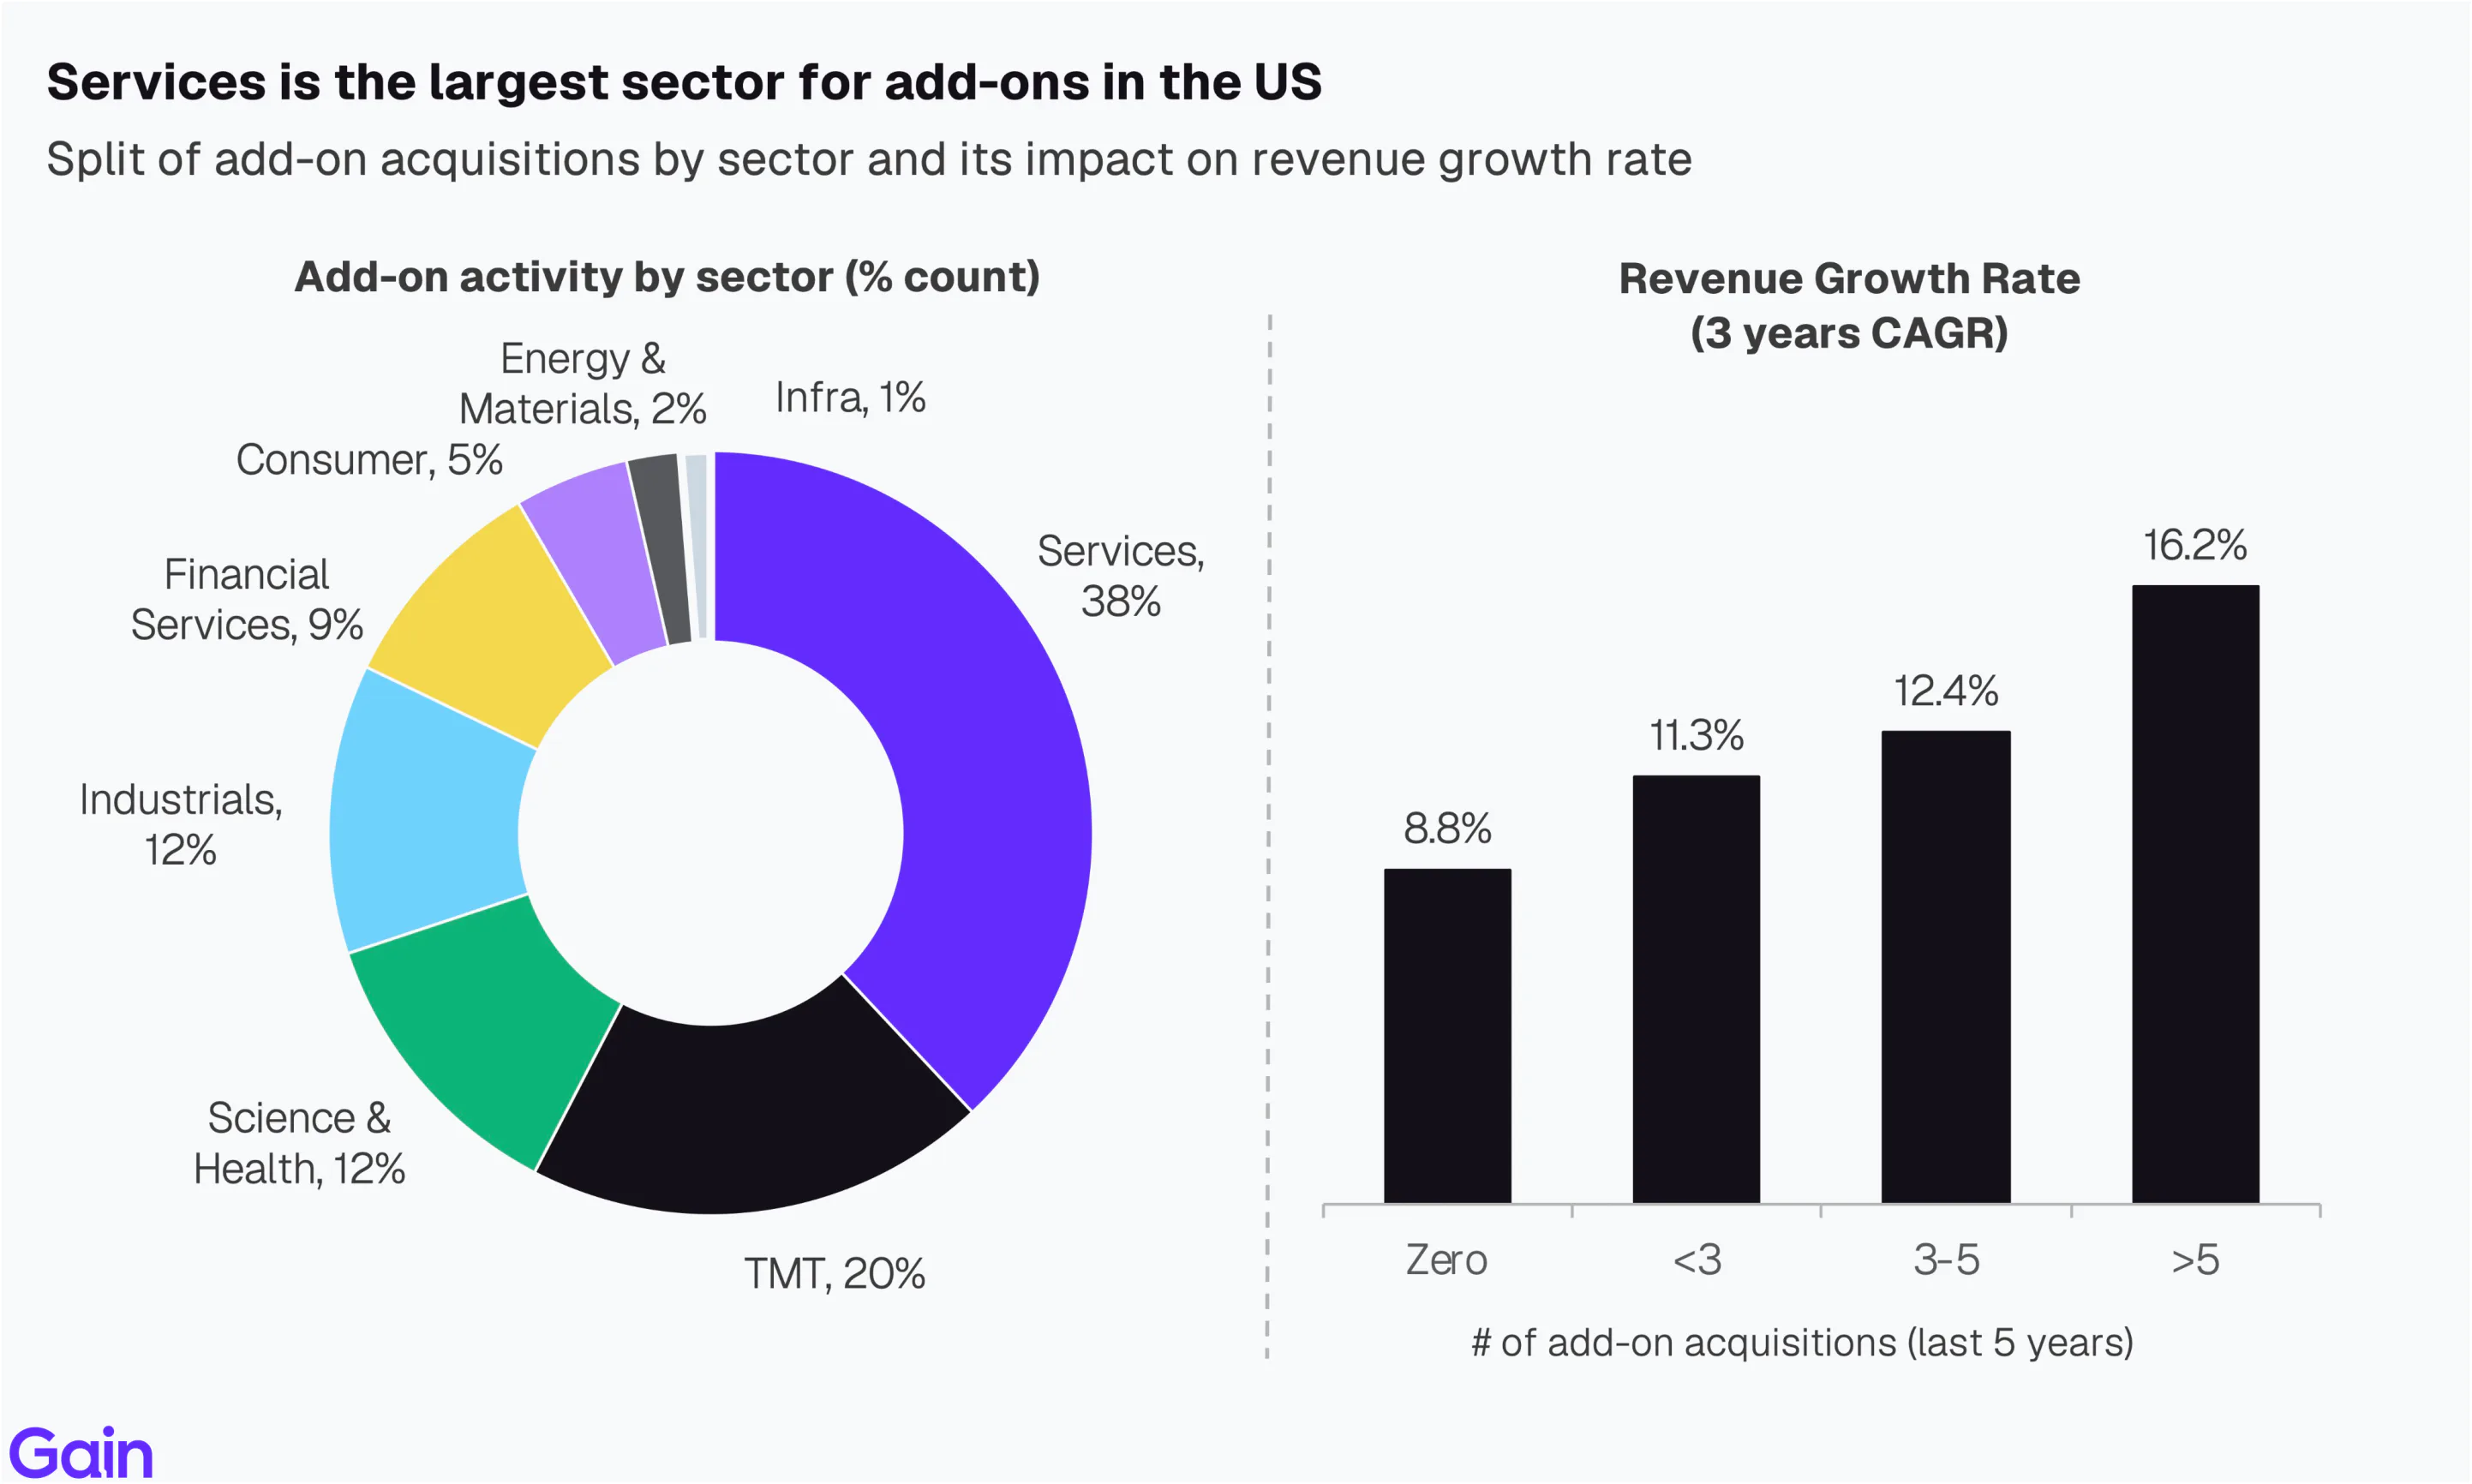
At the asset level, Services (50%) and TMT (49%) show the highest levels of buy-and-build activity. In Services, market fragmentation and limited organic growth potential make M&A essential for value creation, with sponsors capturing multiple arbitrage by consolidating smaller operators into scaled platforms. In TMT, buy-and-build is driven by the need to acquire complementary technology capabilities and expand product suites faster than organic expansion allows.

Chapter 04: Growth & Multiples
Revenue growth is the key driver of value creation. It accounts for 57% of value creation over the last decade. Its share has risen from 44% of value creation in 2019 to 75% in 2025. The share of multiple expansion, in contrast, has fallen from 46% in 2019 to 8% last year, as valuations have come down. Looking ahead, we expect revenue growth to remain the primary driver of value creation, especially as interest rates still remain high and multiples show no signs of recovery.

TMT (14.5%), Financial Services (14.5%), and Services (12.5%) are the fastest-growing sectors among US PE-backed assets. Energy & Materials (4.7%), Science & Health (6.6%), and Industrials (8.3%), in contrast, have lagged behind. We expect TMT revenue growth to moderate from here on, as AI puts pricing and top-line pressure across certain software categories.

PE multiples dropped to 12.0x, now compared to 16.0x seen during 2021. TMT saw the sharpest valuation drop. Also, the valuation multiples for the US assets are higher than European assets.
Methodology
The data for this report comes from Gain.
We define PE-backed entries as those in which a PE firm took a minority or majority stake. We define PE-backed exits as those in which a PE firm sold a minority or majority stake. We exclude any VC rounds from our analysis. Both entries and exits exclude aborted deals.
We only focused our analysis on assets HQ’d in the US.
For deals without disclosed valuations, we estimate deal values using an EV/EBITDA multiple approach based on comparable transactions and company EBITDA. Deal values are also adjusted for the estimated ownership share of each deal. We estimate the deal count for the last 4 quarters based on prior deal history and the percentage of deals that are announced or added post-quarter close.
Our historical data might change as we add and update new deals to the platform.
For metric calculations, we only included assets that had a hand-curated profile on Gain (10+ hours of primary research). Where possible, we have used 2026 and last reported metrics. But in cases where numbers are still being reported, we have relied on metrics from previous years.
All EBITDA-related aggregates such as EBITDA margin and EV/EBITDA multiples exclude Financial Services from calculations.
Related Research
Discover our proprietary reports on investors, assets and PE deals.